How to Budget With an Irregular Income (With a Real Example)
When your pay changes every month, a normal budget falls apart. How to budget on your lowest month, pay yourself from a buffer account, and handle taxes, with a full example.
By Jonathan Seal, Founder, FIRE Institute
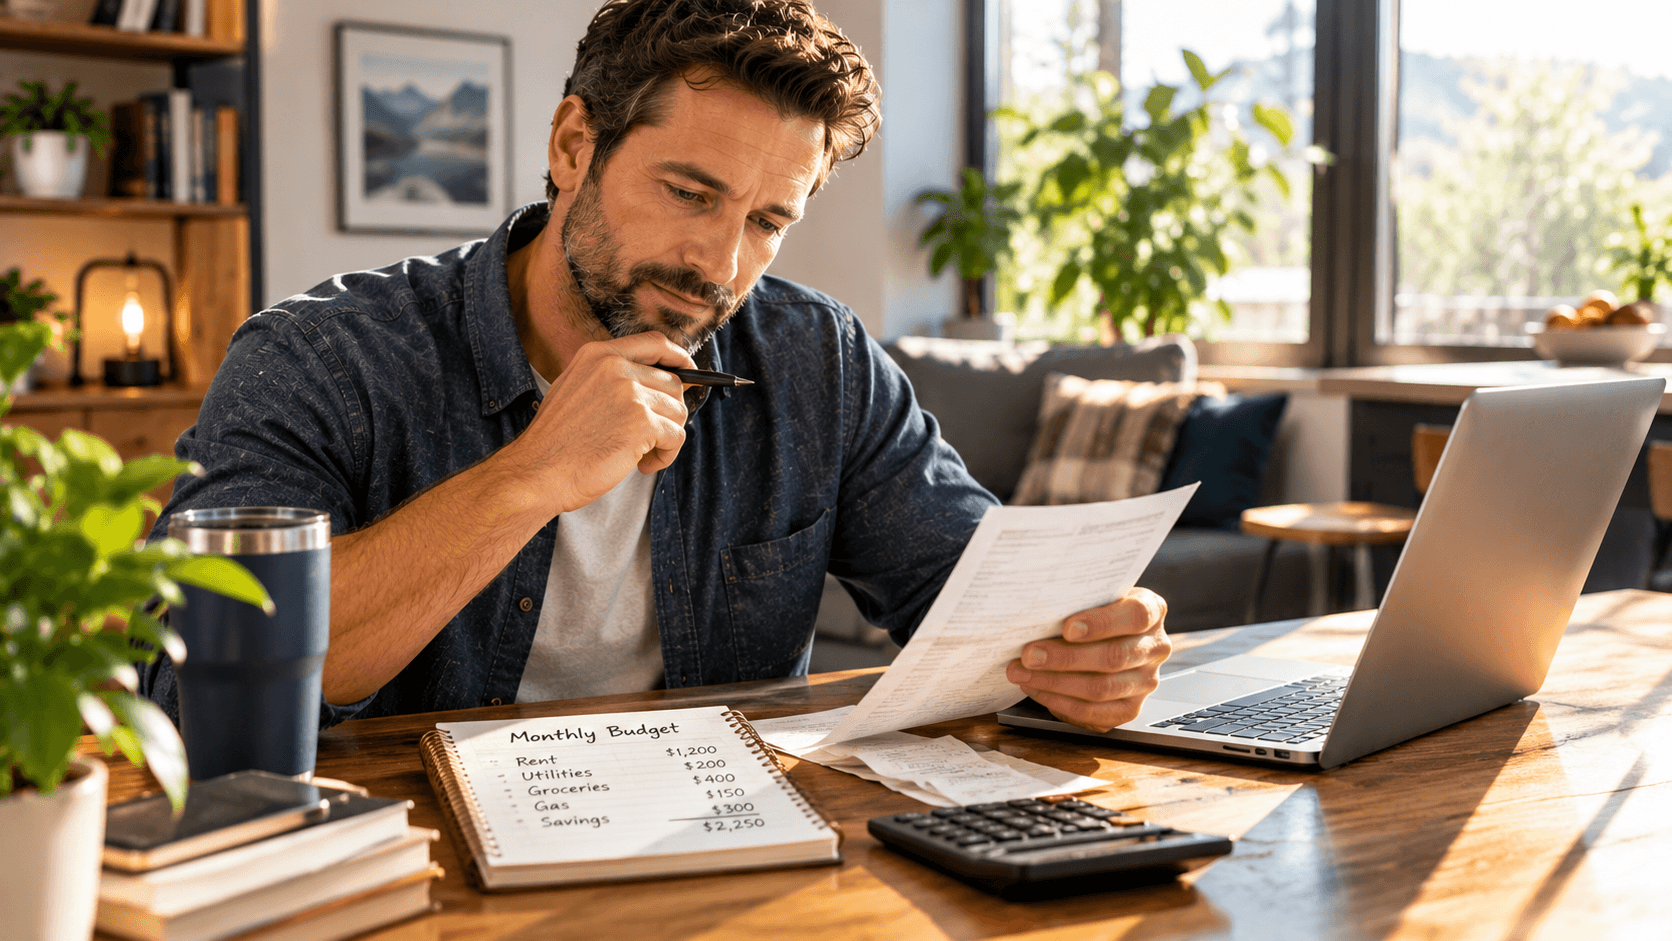
The short answer: budget on your lowest month, not your average. Put everything you earn into one account, pay yourself the same "paycheck" from it every month, and give whatever's left a job.
That works whether you freelance, work on commission, live on tips, drive for an app, or earn most of your money in one season. Here's how to set it up, with a full year of numbers so you can see it work.
Why a normal budget breaks
Standard budgeting advice assumes the same paycheck every two weeks. So people with uneven pay do the natural thing and budget on their average.
The trouble is that you never get paid the average. You get paid a lot one month and not much the next. In the good month the money feels like extra, and it gets spent. In the lean month the rent is still due, and it goes on a credit card.
Here's a year of take-home pay for a freelancer, after setting money aside for taxes:
| Month | Take-home | Month | Take-home |
|---|---|---|---|
| Jan | $3,200 | Jul | $2,800 |
| Feb | $2,600 | Aug | $3,400 |
| Mar | $4,100 | Sep | $4,600 |
| Apr | $3,800 | Oct | $3,100 |
| May | $2,900 | Nov | $4,400 |
| Jun | $5,200 | Dec | $2,700 |
That's $42,800 for the year, or about $3,570 a month on average. But seven of those twelve months came in below the average. A budget built on $3,570 would have run short more often than not.
Step 1: Find your lowest month
Pull up your last 12 months of deposits, or as many as you have. If you're self-employed, use what's left after business costs and taxes. Write down each month and circle the lowest.
In our example, that's $2,600.
If your lowest month was a fluke, like a month you were sick or between contracts, it's fine to use the second-lowest instead. Just don't talk yourself up to the average.
Step 2: Build a budget that fits that number
Now write a budget that works on $2,600, starting with the things that have to get paid:
| Essentials | Each month |
|---|---|
| Rent | $1,150 |
| Groceries | $350 |
| Car and gas | $330 |
| Health insurance | $300 |
| Utilities and phone | $220 |
| Debt minimums | $150 |
| Total | $2,500 |
That leaves $100 for everything else in a lean month. Tight, but every bill gets paid even in your worst month, and that's the whole point.
If your essentials don't fit your lowest month, you've found the real problem, and it's better to find it on paper than in a bad month. Look at the biggest lines first: rent, the car, insurance. The Budget Breakdown Calculator shows each category's share of your pay and flags the ones running high.
Step 3: Pay yourself from a buffer account
This is the part that makes it feel like a normal paycheck.
- Open a separate savings account. Call it your buffer. A high-yield account is best, since the money sits there for a while.
- Send all your income there first, every payment, whenever it comes in.
- Move your "paycheck" to checking on the same day each month. In our example, that's $2,600 on the 1st.
- Pay your bills from checking, like anyone with a steady job.
Your bank account now sees the same income every month, no matter what happened that month. In March, $4,100 comes in, $2,600 goes to checking, and $1,500 stays in the buffer. In February, $2,600 comes in and $2,600 goes out.
To get started, hold back your first month's income and live on your current checking balance if you can. If you can't, start with whatever you have and build up over your next few good months.
Step 4: Give the extra money a job
In our example, the year brings in $42,800 and the paychecks use $31,200. That leaves $11,600 sitting above your baseline. Decide now where it goes, so it doesn't quietly become spending.
When the buffer grows, send the extra down this list, in order:
- Fill the buffer to one month's paycheck, then build it to two or three.
- Build a starter emergency fund: one month of expenses, and at least $2,000.
- Pay off high-interest debt, anything above roughly 7%.
- Finish your emergency fund. With income that changes month to month, plan on more than someone with a steady paycheck. Here's how to work out your number.
- Invest for the long term. Start with a Roth IRA. Here's how to open one.
I'd also keep a small slice for fun, even 10%. If a great month never feels like a great month, you won't stick with this.
Your buffer and your emergency fund do different jobs. The buffer smooths out your normal ups and downs. The emergency fund is for when something goes wrong: the car dies, or your biggest client leaves. Keep them apart, so one bad surprise doesn't take your paycheck with it.
Step 5: If you're self-employed, set aside taxes first
Nobody withholds taxes for you, so every payment you get has some of the government's money in it. Before anything goes to your buffer, move a share of each payment to its own savings account, and don't touch it.
There's no official percentage. Self-employment tax alone is 15.3% on 92.35% of your profit, before any income tax, so set aside at least 25%, and 30% if your income is higher or your state has an income tax. A tax professional can give you a better number once you have a year of income behind you.
The IRS generally expects quarterly payments if you'll owe at least $1,000 for the year. The due dates are April 15, June 15, September 15 and January 15. Put them on your calendar now, because missing them can mean a penalty.
If this is a side hustle on top of a job, the Side Hustle Income Calculator shows what you'd actually keep after setting taxes aside.
What to do when things change
- A month below your baseline. Pull the difference from the buffer. That's what it's for. Then refill it from your next good month.
- A long slump. If the buffer is running low and more lean months are coming, cut back to essentials early. It's much easier to do with two months left than with two days left.
- A huge month. Follow the list in Step 4. Don't raise your spending because of one great check.
- Your income really has gone up. Look at the last 12 months again every six months or so. Once you have two or three months in the buffer and your lowest month has grown, give yourself a raise.
Don't let this slow down your FIRE plan
Uneven pay doesn't rule out financial independence. It just means measuring over a year instead of a month. Add up what you saved and invested over the whole year, then divide by what you took home. That's your real savings rate, and the Savings Rate Calculator shows how many years it takes you to get there.
Good months can even help, since a big payment can go straight to your investments once the buffer is full.
Your next step
Pull up your last 12 months of deposits and circle the lowest one. That's your new budget number, and it takes about ten minutes to find.
If you'd like more help, the 30-Day FIRE Kickstart has a self-employed path for the days that deal with paychecks and taxes.